
04 / Widgets · Event Odds
Event Odds
The next three macro releases for your market: the odds of a cooler, in-line or hotter print, the options-implied move, and how the market reacted before.
Event Odds lists the next three economic releases that matter for the workspace market (CPI, jobs, retail sales, Fed decisions and more), with a countdown to each. Every row shows:
| Element | What it is |
|---|---|
| Headline | The market's median expectation, or the most likely Fed outcome |
| C / = / H | Market odds of a cooler, in-line or hotter result than expected |
| ▲ ▼ | How the market moved after past releases in that scenario, shown only where the history gives a clear lean (◆ mixed, – no clear edge, · not enough history) |
| IM | The options-implied move to the expiry covering the release, and the expected move on the release day itself |
When too little is traded on a release to trust the odds, the row says thin market, odds hidden rather than showing unreliable numbers.
Marked (Beta) in the widget picker: it is newer, and some of the data behind it can lag the live market by several minutes.
Practical application#
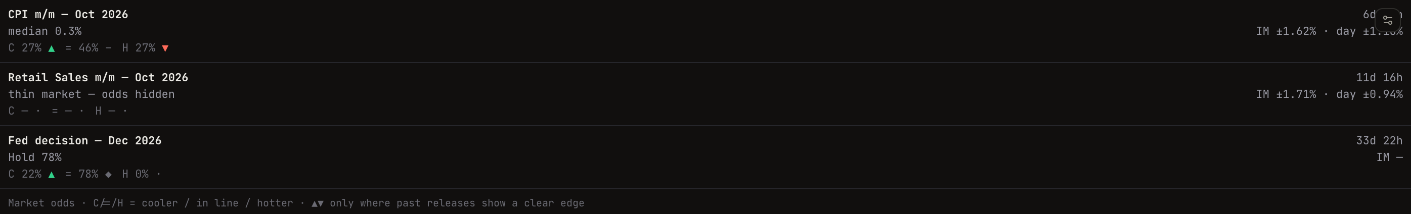
Reading it. The next release for NQ is CPI in 6 days 16 hours, with a median expectation of 0.3%. The market gives 27% to a cooler print, 46% to in line and 27% to hotter. History has a clear lean on both tails: ▲ after cooler prints and ▼ after hotter ones, with no edge when it comes in line. Options price ±1.62% to the CPI expiry, ±1.18% of it on the day. Retail Sales follows, but its odds are hidden because the market is thin. The Fed in December is priced at Hold 78%.
What it means. CPI is a real two-sided risk: about a one-in-four chance each way of a surprise, and NQ has moved the same way after past surprises. Options already expect a move of more than 1% on the day.
How to use it.
- Before the release, size for the implied move. A ±1.18% day on NQ is over 300 points; stops tighter than that can be hit by noise.
- Where history shows ▲ or ▼, have a plan for both outcomes instead of guessing the print.
- Big in-line odds with no edge suggest a muted reaction unless the surprise is large.
- Thin market, odds hidden: rely on the implied move only.
While CME is closed, a predicted reopening price for ES, NQ and GC, with direction, a likely range and where it lands against the levels.
The options-implied range around price for every horizon, with today's 1D band and how much of it is used.
The options-implied probability cone for price over the coming weeks, next to the recent candles.